The Interest Rate Hiding Behind the Exam Voucher
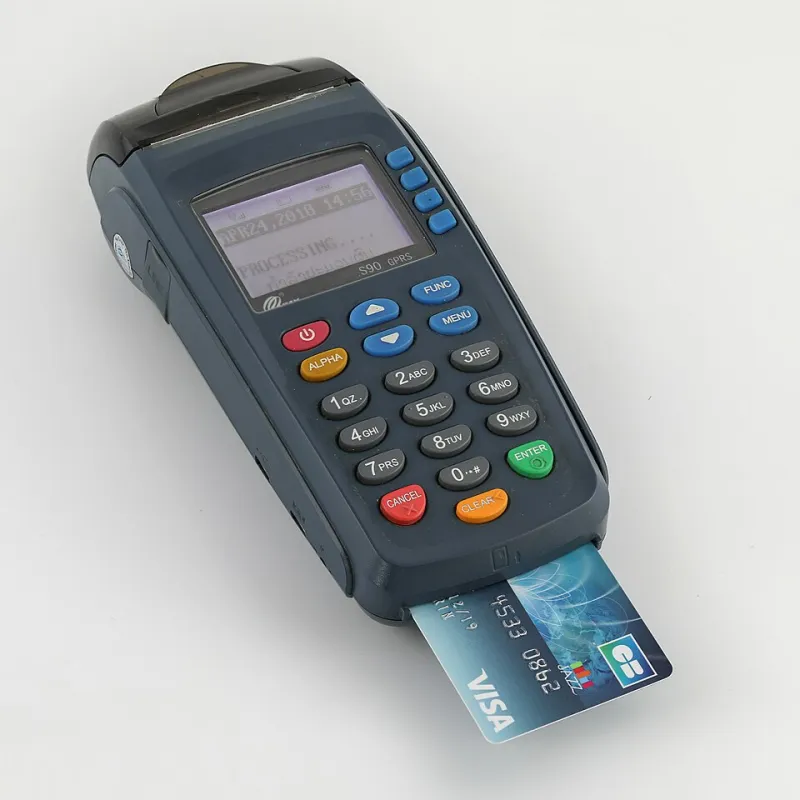
Photo: Basile Morin, CC BY-SA 4.0, via Wikimedia Commons
A certification purchase feels small at the moment of checkout. Two hundred fifty dollars for an exam, sixty for a practice test bundle, forty a month for a lab environment, and then a bootcamp deposit that arrives with a payment plan attached. Because each transaction is individually modest, the aggregate rarely gets examined. Then the statement arrives, the promotional window closes, and a career investment quietly becomes a consumer debt.
This is not an argument against spending money on credentials. It is an argument for reading the annual percentage rate before the voucher code.
The Number That Does Not Appear on the Checkout Page
Certification vendors advertise total price, not financing cost. A candidate who pays $1,400 for a bundle of exam vouchers and prep materials sees $1,400. A candidate who puts that same $1,400 on a card at roughly 25 percent APR sees something else entirely once the balance rolls forward.
Run the arithmetic on a larger case. A $3,000 balance — a mid-priced bootcamp deposit plus two vouchers and a year of lab access — at an illustrative 24.99 percent APR, repaid at $100 per month, takes close to four years to clear. Total payments land near $4,760. The interest alone, roughly $1,760, exceeds the cost of every exam in the CompTIA core sequence.
The pattern repeats at smaller amounts. What makes it insidious is that the monthly payment feels manageable, so the balance persists long after the certification is earned and, in some cases, after it has expired.
Why Certification Debt Behaves Differently From Other Borrowing
Three features distinguish this kind of debt from a car loan or a mortgage.
First, the asset depreciates on a schedule the borrower does not control. A credential that helps land a job in month three may be worth considerably less on a resume in year three if no relevant work experience accumulated behind it. The loan outlives the advantage.
Second, the return is probabilistic. A bootcamp graduate with a strong network and a clean interview lands quickly. A bootcamp graduate in a slow hiring market may wait months. The debt does not adjust to the outcome.
Third, promotional financing frequently includes deferred interest. A zero-percent offer that runs for twelve months is genuinely free only if the balance reaches zero before the deadline. Miss it by a week, and many agreements apply retroactive interest to the original balance, not merely to what remains. This is a common and expensive misunderstanding.
There is a secondary consideration for roles in financial services, defense contracting, and some security-cleared positions: employers in those sectors may run credit checks, and high revolving utilization can complicate an otherwise strong application.
Four Lower-Risk Routes Worth Exhausting First
Employer reimbursement. Many employers fund certifications, particularly when the credential maps to a documented business need. The pitch that works is specific: name the certification, name the internal system it supports, and propose a reimbursement agreement with a service commitment. Approved reimbursement frequently covers exams but not bootcamps, so ask which categories qualify before enrolling.
Community college credit pathways. A single course at a public community college often costs less than a commercial bootcamp week, and it comes with access to federal financial aid, an instructor, and a transcript. Several states fund noncredit IT academies through their community college systems at minimal cost to the student.
Voucher bundles with retake protection. Vendors and authorized resellers sell exam vouchers packaged with a free retake. For a candidate who is genuinely ready but anxious, this converts one high-risk purchase into one lower-risk purchase and eliminates the scramble to fund a second attempt.
Zero-interest installments, read carefully. Some training providers offer their own installment plans at zero percent, separate from any credit card. The terms vary widely; the ones worth signing disclose the total, the schedule, and the consequence of a missed payment in plain language.
Public workforce funding is worth a mention as well. Workforce Innovation and Opportunity Act programs in many localities cover training for displaced workers and career changers, and eligibility is broader than most people assume.
If Credit Is Genuinely the Only Option
Sometimes it is. A candidate with a firm interview timeline and no other liquidity may reasonably borrow. In that case, a few practices reduce the damage.
Charge only what you can repay within two statement cycles, and pay the balance before the statement date rather than the due date, which keeps reported utilization low. Automate the payment. Decline cash advances and convenience checks, which typically carry higher rates and begin accruing interest immediately. And keep the certification purchase separate from everyday spending so the balance remains visible rather than blending into groceries.
Above all, decide the number before the checkout page decides it for you. A credential financed badly costs more than a credential deferred by three months while the funding gets sorted out.